
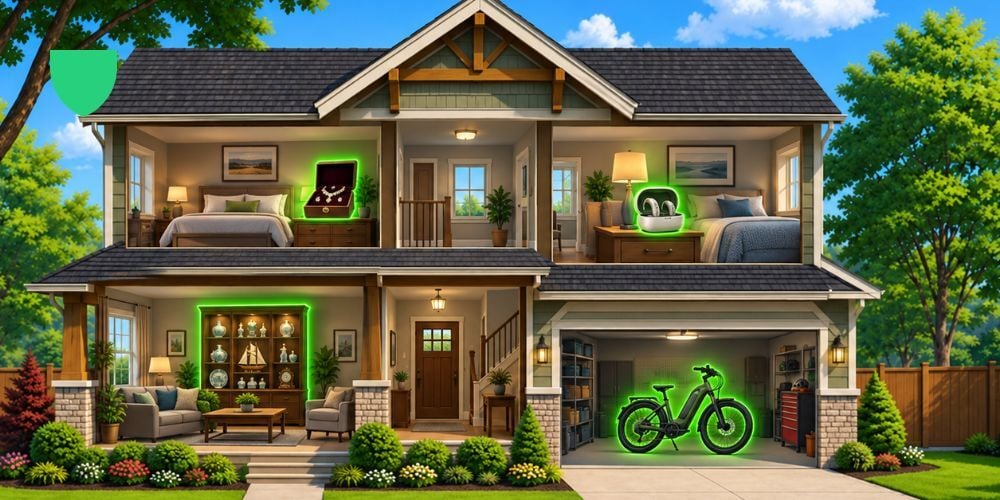
Home insurance protects more than the building you live in. It also helps protect the things you own. However, some belongings have special coverage limits that can be much lower than your total contents coverage. Scheduling certain items on your home insurance can help fill this gap. Let’s look at how special limits and scheduled items work, and when you may want to speak with your insurance broker.
What Should You Know About Scheduling Items on Home Insurance?
- What are special limits on a home insurance policy?
- What does it mean to schedule an item on home insurance?
- What items should you consider scheduling on your home insurance?
- Does scheduling an item give you better coverage?
- What do you need to schedule something on your home insurance? Do you need an appraisal?
- How much does it cost to schedule an item on home insurance?
- How do you know if something in your home should be scheduled?
1. What Are Special Limits on a Home Insurance Policy?
Your home insurance policy may provide a large amount of coverage for your belongings. This is often called contents coverage or personal property coverage. However, that does not mean every item you own is covered up to the full contents limit.
Insurance policies can have special limits for certain types of property. A special limit is the most the insurance company will pay for a certain type of item or loss. These limits can apply to things like jewelry, bicycles, collectibles, cash, sporting equipment, and other property.
For example, imagine your policy provides $100,000 of contents coverage. You might think a $15,000 engagement ring would easily fit within that amount. However, your policy could have a much lower special limit for jewelry. If the ring is stolen or destroyed, that special limit could affect how much you can claim.
Special limits apply to the entire category of that type of item. If you have a special limit of $10,000 for jewelry, that applies to every piece of jewelry that you own. If you were to have a claim where $20,000 of jewelry was lost, the special limit would only cover up to $10,000. Scheduling your jewelry would cover your jewelry up to the scheduled limit in the event of a loss.
Special limits vary between insurance companies and policies. Your insurance broker can help you find the limits that apply to your coverage.
2. What Does It Mean to Schedule an Item on Home Insurance?
Scheduling means specifically listing an item or collection on your insurance policy. A value is assigned to that property, and additional coverage is provided for it. Think of it as giving an important possession its own place on your policy.
For example, suppose you own a $15,000 engagement ring. Your home insurance policy may have a special limit for jewelry that is lower than the value of the ring. You may be able to schedule the ring for its value instead. The ring would then have coverage based on the terms of the scheduled coverage rather than relying only on the standard jewelry limit.
Scheduling can also be used for collections. Depending on the insurance company, a collection may have a total insured value as well as limits for individual pieces within the collection.
3. What Items Should You Consider Scheduling on Your Home Insurance?
There are many things you may be able to schedule. What you should schedule depends on what you own, how much it is worth, and the special limits in your policy.
Common examples can include:
- Jewelry
- Fine art
- Antiques
- Bicycles or electric bicycles
- Musical instruments
- Sporting equipment
- Utility trailers
- Coins and banknotes
- Stamps, cards, comics, and other collections
- Other valuable collectibles or personal property
You do not need to schedule every expensive thing you own. The first step is comparing the value of your belongings with the limits in your policy.
For example, a household with two expensive bicycles could have very different insurance needs from a household with two basic bikes. The same applies to jewelry, golf equipment, instruments, and collections.
The value of collections can also sneak up on you. You might have spent years building a collection one piece at a time. Today, the total collection could be worth much more than you realize.
4. Does Scheduling an Item Give You Better Coverage?
It can. The main reason to schedule an item is usually to provide coverage beyond a special limit that would otherwise apply. Depending on the insurer and policy, scheduled coverage may also provide broader protection for certain types of loss.
For example, losing a ring may be treated differently from having it stolen during a break-in. Scheduled coverage may offer protection for situations that are not covered in the same way under standard contents coverage. The additional coverage for “mysterious disappearance” is a tremendous value add for most customers when scheduling items.
An additional coverage benefit to scheduled items can be the claims status and deductible. While it does depend on the insurance provider, many companies will not change your claims-free status on your home insurance if you only make a claim on scheduled item. Scheduled items also typically benefit from lower insurance deductibles in the event of a claim. You can often set the deductible at $100 or even less.
While many find it easier and/or cheaper to schedule their trailer on thier homes insurance, rather than having a seperate policy for it, we generally do not recommend this. A claim against your trailer while scheduled can create a claim on your home insurance.
The exact coverage depends on the insurance company and policy. This is an important reason to talk with your broker before scheduling something. The goal is not simply to put a higher dollar amount beside an item. You should also understand what the scheduled coverage protects against, what exclusions apply, and whether a deductible applies.
5. What Do You Need to Schedule Something on Your Home Insurance? Do You Need an Appraisal?
Your insurance company will normally want proof of what the item is and how much it is worth. For a newer purchase, a receipt or bill of sale may be enough. The insurance company may also ask for photos or other information about the item.
For older, rare, collectible, or high value items, you may need a professional appraisal. An appraisal can be especially important when the item's value is difficult to determine. An antique passed down through your family may have great sentimental value, but insurance needs a dollar value for the item.
The same problem can occur with art, jewelry, coins, sports memorabilia, and other collectibles. Their value can also change over time. Insurance companies can have different rules about how recent an appraisal needs to be but the typical rule is no more than 5 years old. Before paying for one, talk with your broker about what documents your insurance company requires.
6. How Much Does It Cost to Schedule an Item on Home Insurance?
There is no single price for scheduling an item. The additional premium can depend on the type of property, its insured value, where you live, the insurance company, and the coverage being provided. A $5,000 bicycle will not necessarily cost the same to schedule as a $20,000 ring or a large collection. This is why it is best to ask your broker for a quote. As a general rule, the higher the cost of the scheduled item, the higher the premium. $10-$500/year is relatively standard depending on the item and value.
The important comparison is not only how much the extra coverage costs. You should also consider how much you could lose if an expensive item is only protected up to the standard special limit. Your broker can show you the cost and explain what additional coverage you are getting for that price.
7. How Do You Know If Something in Your Home Should Be Scheduled?
Start by thinking about the possessions that would be expensive or difficult to replace. Have you recently bought an engagement ring? Do you own an expensive bicycle? Have you built a large collection? Do you own valuable art, antiques, instruments, or sporting equipment?
Next, find out what special limits apply to those items on your home insurance policy. If the value of an item or collection is higher than the available coverage, it is worth speaking with your broker about scheduling it. Even when the value is below the limit, you may still want to ask what protection your policy provides.
It is also a good idea to review your belongings from time to time. A collection can grow, jewelry can increase in value, and a new purchase can change your insurance needs.
Final Thoughts
Having enough contents coverage is important, but the total contents limit does not tell the whole story. Special limits can affect how much coverage you actually have for certain valuable belongings. Scheduling an item can help you protect property that goes beyond those limits. The right solution will depend on the item, its value, your policy, and your insurance company. The insurance brokers at Armour Insurance can help you review your special limits and determine whether any of your belongings should be scheduled.