
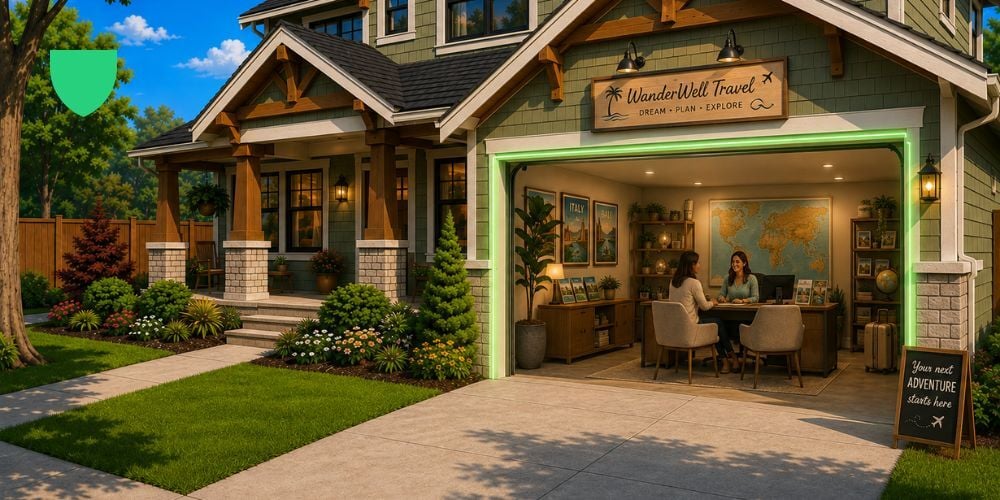
Running a business from home can be a great way to keep costs down, but it can also change your insurance needs. Your home may be insured, but that does not mean your business activities, equipment, or liability are covered.
The type of business you run, whether customers visit your home, and where you perform your work can all affect your coverage. If you run any type of business from your home, it is important to let your insurance broker know. This can help you understand your risks and make sure you have the right coverage before a loss happens.
What Should you Know About Home-Based Businesses and Home Insurance?
- Does home insurance cover a home-based business?
- Do I need to tell my insurance company about a home-based business?
- What happens if I do not disclose my home-based business?
- What types of home-based businesses can be covered by home insurance?
- What types of home-based businesses do not typically qualify for coverage under home insurance?
- When does a home-based business need commercial insurance?
- Does home insurance cover business activities away from my property?
- Can I run a daycare or day home with just house insurance?
- What insurance do I need for business equipment, customers, and liability at home?
- Do farms need home insurance or commercial insurance?
1. Does Home Insurance Cover a Home-Based Business?
Home insurance may cover some home-based businesses, but you should never assume your business is automatically covered. The insurance company needs to know about the business and approve it.
Whether your business can be added to your home insurance depends on what you do and how the business operates. Your insurer may look at things like whether customers visit your home, what equipment or products you keep there, and the type of work you perform.
Even when a home-based business is approved, the coverage available through a home insurance policy can be limited. If your business has risks that your home policy cannot properly cover, a commercial insurance policy may be a better fit.
2. Do I Need to Tell my Insurance Company About a Home-Based Business?
Yes. If you operate a business from your home, you should tell your insurance broker or insurance company.
Even a small or part-time business can change the risks at your property. You may have customers visiting, business equipment in the home, products stored on site, or other activities that were not considered when your home policy was issued.
Disclose the business before you begin operating. Your broker can then help determine whether your home insurer will accept the business and whether you need additional coverage.
3. What Happens if I do not Disclose my Home-Based Business?
Not telling your insurer about a home-based business can create serious problems.
An undisclosed business could affect your insurance coverage. Depending on the policy and circumstances, a claim could be denied, coverage could be limited, or there could be the risk of being cancelled for misrepresentation. A misrepresentation cancellation can make it incredibly challenging to regain insurance.
The safest approach is simple. Tell your broker about the business and make sure the insurance company approves it.
4. What Types of Home-Based Businesses can be Covered by Home Insurance?
Some lower risk businesses may be considered by home insurance companies. Examples can include:
- Florists
- Bookkeepers
- Accountants
- Travel agents
- Hairdressers
This does not mean every insurer will accept every business. How the business operates matters too. For example, an insurer may want to know whether customers visit your home, how much business equipment you have, whether you keep inventory, and how much income the business earns.
Your broker can provide these details to the insurance company and find out what coverage may be available.
5. What Types of Home-Based Businesses Do Not Typically Qualify for Coverage Under Home Insurance?
Some businesses have risks that home insurance companies are not typically willing to cover. Examples can include:
- Waxing services
- Tattoo artists
- Piercing services
- Cosmetic fillers and injectables
These businesses can involve greater liability risks because they provide services directly to a person's body. A standard home policy is not suitable for these risks. If your home insurance does not allow for the type of business you wish to operate, you will need a commercial space with a commercial insurance policy to proceed with operations.
6. When Does a Home-Based Business Need Commercial Insurance?
Any time you are running a business, it is a recommended to get a commercial insurance policy. Home based business coverage under a personal home policy is often limited. A commercial policy can provide broader coverage for things such as business property, liability, equipment, and other risks related to your operations.
Small business insurance can also be more affordable than many business owners expect. Getting commercial insurance is not just about meeting an insurance requirement. It is also a chance to look at the risks in your business and make sure you have appropriate protection if something goes wrong.
7. Does Home Insurance Cover Business Activities Away from my Property?
The second your business leaves the property, so does your insurance coverage. If your business activities are off the property, you will almost certainly not have coverage through your home insurance. It is incredibly important to get a commercial insurance policy.
Your home policy is primarily intended to insure your home and your personal activities. There can be a big difference between doing bookkeeping from a home office and travelling to customers' properties to perform work.
8. Can I Run a Daycare or Day Home with Just House Insurance?
Daycares and day homes need special attention because you are caring for other people's children in your home. Some home insurance companies may allow a daycare or day home but are limits and conditions. One important limit can be the number of children you are allowed to care for. The legal limit and the limit allowable by insurance are often different. Commercial insurance premiums for daycares and day homes are generally quite reasonable and affordable.
Do not assume your regular home insurance automatically covers a daycare or day home. Tell your broker what you are planning to do, including how many children will be in your care. Your insurer can then determine whether the risk is acceptable and what coverage is required.
9. What Insurance do I Need for Business Equipment, Customers, and Liability at Home?
This depends on how your business operates. Think about what would happen if your business equipment was damaged or stolen. You should also think about what could happen if a customer was injured while visiting your home or if your work caused injury or property damage.
A home policy may provide little or no coverage for some business-related losses. Commercial insurance can provide broader protection that is designed around the needs of a business. This is one reason it is important to explain your full business operation to your broker, rather than simply saying that you work from home.
10. Do Farms Need Home Insurance or Commercial Insurance?
Farms are a little different because they can include both a home and a business operation. A property may be someone's residence while also producing income through farming. Once a farm is being operated to produce income, it may require specialized farm insurance that addresses both the personal and commercial risks involved.
Your broker can review the residence, farming operations, equipment, buildings, liability risks, and other details to help determine the coverage you need. Farms are typically considered commercial insurance.
Final Thoughts
Running a business from home does not always mean you need a large commercial insurance policy. It does mean you should tell your insurance broker what you are doing. Your insurer may approve the business under your home insurance, additional coverage may be needed, or a commercial policy may be the better choice. The important thing is to find out before a loss happens.
A conversation with your broker can also help you spot risks you may not have considered. If you run a business from home or are thinking about starting one, our team would be happy to assist you.